A smooth audit starts well before the fieldwork begins. Use this checklist to get your books, records, and team ready, and to avoid last-minute scrambles.
A smooth audit starts well before the fieldwork begins. Use this checklist to get your books, records, and team ready, and to avoid last-minute scrambles.
If audit season makes you groan, you’re not alone. The word “audit” carries a lot of baggage, but a well-planned audit can be one of the most useful things that happens to your organization all year. Here is a practical guide to preparing, drawn from a GGFOA presentation on getting audit-ready.
Most growing businesses reach a point where the books can no longer be a side task. You’re up late reconciling accounts, a part-time bookkeeper is stretched thin, and nobody is sure whether the numbers are right until tax season. Client Accounting Services (CAS) exists for this moment.
Lease and subscription arrangements can be easy to overlook—but keeping an accurate, up-to-date listing of lease and subscription liabilities is an important part of maintaining reliable financial records.
Our firm offers a nonattest service designed to help governmental clients stay organized and keep pace with the requirements of GASB 87, Leases, and GASB 96, Subscription-Based Information Technology Arrangements (SBITAs).
Securing in-kind donations is vital for any non-profit or charitable organization, but just as important is accounting for them properly. In June 2020, the Financial Accounting Standards Board introduced changes to the General Accepted Accounting Principles (GAAP) for documenting and presenting the value of in-kind donations in financial statements. This article provides an overview of the changes and what you need to know.
As the 2026 calendar closes in on the October 15th deadline, many plan administrators are unsure if their employee benefit plan requires an audit. Our team can help you determine if your plan requires an audit or if your plan is approaching the audit threshold for the first time. With this knowledge, we can either act quickly and efficiently to ensure your audit is completed before the October 15th deadline or work with you to ensure you are properly prepared for your first audit in 2027.
If your organization solicits or accepts donations in Georgia, there’s a good chance you have a registration requirement you may not know about — and a reporting obligation that scales with how much your nonprofit brings in.
Here’s what Georgia nonprofits need to know.
Rushton Recognized Among the Nation’s Top Accounting Firms by Inside Public Accounting
Rushton names Elisabeth Baldwin Managing Partner of Rushton Wealth Management
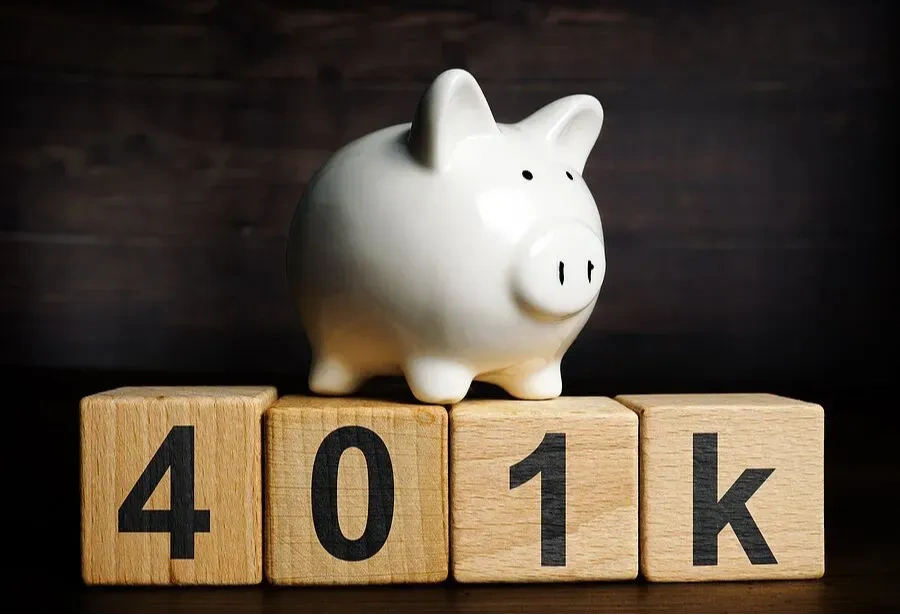
Even if retirement isn’t in your immediate future, saving and investing now can help you live comfortably after you’re done working. One of your most impactful opportunities to save, and even earn, over time is by investing in your 401(k). You may be familiar with some of the benefits, from employer contributions to reduced taxes. But did you also know that your savings can compound over time, generating even more income for retirement?
If you like the sound of “automated savings” that can help you live the retirement lifestyle you deserve, then here are five more reasons to contribute to your 401(k):
1. 401(k) Contributions Are “Before Tax” Money
With a traditional 401(k), your contributions are deducted from your gross income. In other words, any tax-deductible contributions are removed from your paycheck before taxes. Taxes aren’t deducted from your contributions or any investment earnings from that account until you withdraw the money.
2. When You Finally Pay Taxes on Your 401(k), It May Be at a Lower Rate
A 401(k) can have significant tax advantages. Here’s why. Your retirement contributions are deducted from each paycheck pre-tax. Since traditional 401(k) contributions are made before taxes, they don’t count toward your taxable income, which means your tax burden for the year will be lower.
Although you’ll pay taxes on the income you withdraw from your traditional 401(k) later on, there’s a good chance you’ll be in a lower tax bracket once you’re retired and begin making withdrawals. If you have a Roth 401(k), however, you’ll contribute post-tax money to your account, which means your retirement withdrawals are tax-free.
3. Your Employer May Contribute to Your Retirement Plan
One of the biggest advantages of an employer-based 401(k) is that it’s an easy way to start saving for retirement. Not only are your contributions automatically deducted from your paycheck, but your employer may also choose to make matching contributions, up to a certain amount. Any contribution your employer makes is essentially extra savings from the company’s pocket.
Depending on the type of 401(k) you have (Roth or traditional), you’ll owe taxes on funds before they’re added to the account, or whenever you withdraw the funds from the account.
About 401(k) Contributions
A 401(k) is a defined contribution plan that allows you and your employer to make contributions up to a specific dollar amount set by the IRS. This contribution limit changes annually to account for inflation, and the limit is higher for certain age groups. When planning your contributions, be sure to check the latest limits set for your age group.
One of the best ways to get the most out of your 401(k) is to maximize your contributions, meaning you contribute the maximum amount permitted. If your company offers matching contributions, you may want to consider taking full advantage of this added benefit.
Beyond annual contributions to your account from yourself and your employer, you can also earn a rate of return on the money in your account. The more time your contributions remain in your 401(k) account, the greater earning potential they may have.
4. Assets Protected From Creditors
In the event of bankruptcy or issues with creditors, your 401(k) assets are generally safe due to the Employee Retirement Income Security Act (ERISA). Under federal law, any assets that are in your 401(k) are generally protected from claims by creditors. If you owe child support, alimony or back taxes, the IRS may be able to garnish your 401(k) money. However, since the account legally belongs to your employer until you start to withdraw money for income, you have some protection from federal tax liens.
5. You Can Compound Your Money
How does simple savings sound? In the financial world, a compounding 401(k) is about as close as it gets to making money easily. Compound interest refers to interest that’s calculated on the initial amount of your deposit or loan, in addition to interest that accumulates on that amount. Depending on your plan’s policy, interest is often compounded on a daily, monthly, quarterly, or annual basis.
With so many potential benefits, it’s no wonder that 401(k) accounts are a preferred choice for many investors who want to plan and save for retirement. The more money you can save now, the more comfortable your lifestyle might be once you retire. Your 401(k) can also help fund qualified expenses beyond retirement, including healthcare costs, education, or primary residence expenses. Qualifying events like these may enable you to make tax-free early withdrawals without incurring a penalty.
If you have any questions about how to maximize your 401(k) account contributions or want to learn more about your current retirement plan, contact the office for more information.
This material was developed and prepared by a third party for use by your Registered Representative. The opinions expressed and material provided are for general information and should not be considered a solicitation for the purchase or sale of any security. The content is developed from sources believed to be providing accurate information.
For a comprehensive review of your personal situation, always consult with a tax or legal advisor. Registered Representatives of Cetera firms may not give legal or tax advice.
The strategies mentioned may not be appropriate for all investors. Please consult your financial or tax advisor to determine a strategy that works best for you. Retirement plan withdrawals may be subject to taxation and penalties when withdrawn early.
A smooth audit starts well before the fieldwork begins. Use this checklist to get your books, records, and team ready, and to avoid last-minute scrambles.
If audit season makes you groan, you’re not alone. The word “audit” carries a lot of baggage, but a well-planned audit can be one of the most useful things that happens to your organization all year. Here is a practical guide to preparing, drawn from a GGFOA presentation on getting audit-ready.
Most growing businesses reach a point where the books can no longer be a side task. You’re up late reconciling accounts, a part-time bookkeeper is stretched thin, and nobody is sure whether the numbers are right until tax season. Client Accounting Services (CAS) exists for this moment.
Lease and subscription arrangements can be easy to overlook—but keeping an accurate, up-to-date listing of lease and subscription liabilities is an important part of maintaining reliable financial records.
Our firm offers a nonattest service designed to help governmental clients stay organized and keep pace with the requirements of GASB 87, Leases, and GASB 96, Subscription-Based Information Technology Arrangements (SBITAs).
Securing in-kind donations is vital for any non-profit or charitable organization, but just as important is accounting for them properly. In June 2020, the Financial Accounting Standards Board introduced changes to the General Accepted Accounting Principles (GAAP) for documenting and presenting the value of in-kind donations in financial statements. This article provides an overview of the changes and what you need to know.
As the 2026 calendar closes in on the October 15th deadline, many plan administrators are unsure if their employee benefit plan requires an audit. Our team can help you determine if your plan requires an audit or if your plan is approaching the audit threshold for the first time. With this knowledge, we can either act quickly and efficiently to ensure your audit is completed before the October 15th deadline or work with you to ensure you are properly prepared for your first audit in 2027.
If your organization solicits or accepts donations in Georgia, there’s a good chance you have a registration requirement you may not know about — and a reporting obligation that scales with how much your nonprofit brings in.
Here’s what Georgia nonprofits need to know.
Rushton Recognized Among the Nation’s Top Accounting Firms by Inside Public Accounting
Rushton names Elisabeth Baldwin Managing Partner of Rushton Wealth Management